
CARF, CRS 2.0, and jurisdiction-specific requirements land differently market by market. Bring them into one reporting workflow.
The APAC & Middle East Timeline
Roughly five months to get systems ready before the first reporting cycle.
The Platform
Fragmented tools get harder to manage as obligations grow. Taxbit unifies regulatory reporting and expert-built logic on one platform.
01
From raw data to filing
Ingest raw transaction data and produce the finished report, with no data-prep project required first.
02
One integration, many regimes
CARF, CRS 2.0, and local regimes on one stack, one data model, one audit trail. Normalized data teams can query, analyze, and build on.
03
Continuous, not annual
Ingest data year-round and catch errors early, so reporting doesn’t turn into an annual scramble.
Who this is for
Here's where it hits first.
Owns onboarding, data quality, and reporting workflows across jurisdictions.
Relies on reconciled data and outputs the team can stand behind when deadlines hit.
Needs reporting infrastructure that fits the existing stack and without becoming a custom internal build.
01
20M+
Tax forms filed
02
3B+
Digital asset transactions
03
70M
Reporting jurisdictions
Go deeper
The detailed guides our customers use to scope CARF internally.
Get ahead of 2027.
Talk with one of our regulatory experts and see how the platform moves teams from fragmented reporting data to submission-ready outputs.
Common questions
Plain answers on scope, coverage, and how the platform fits.
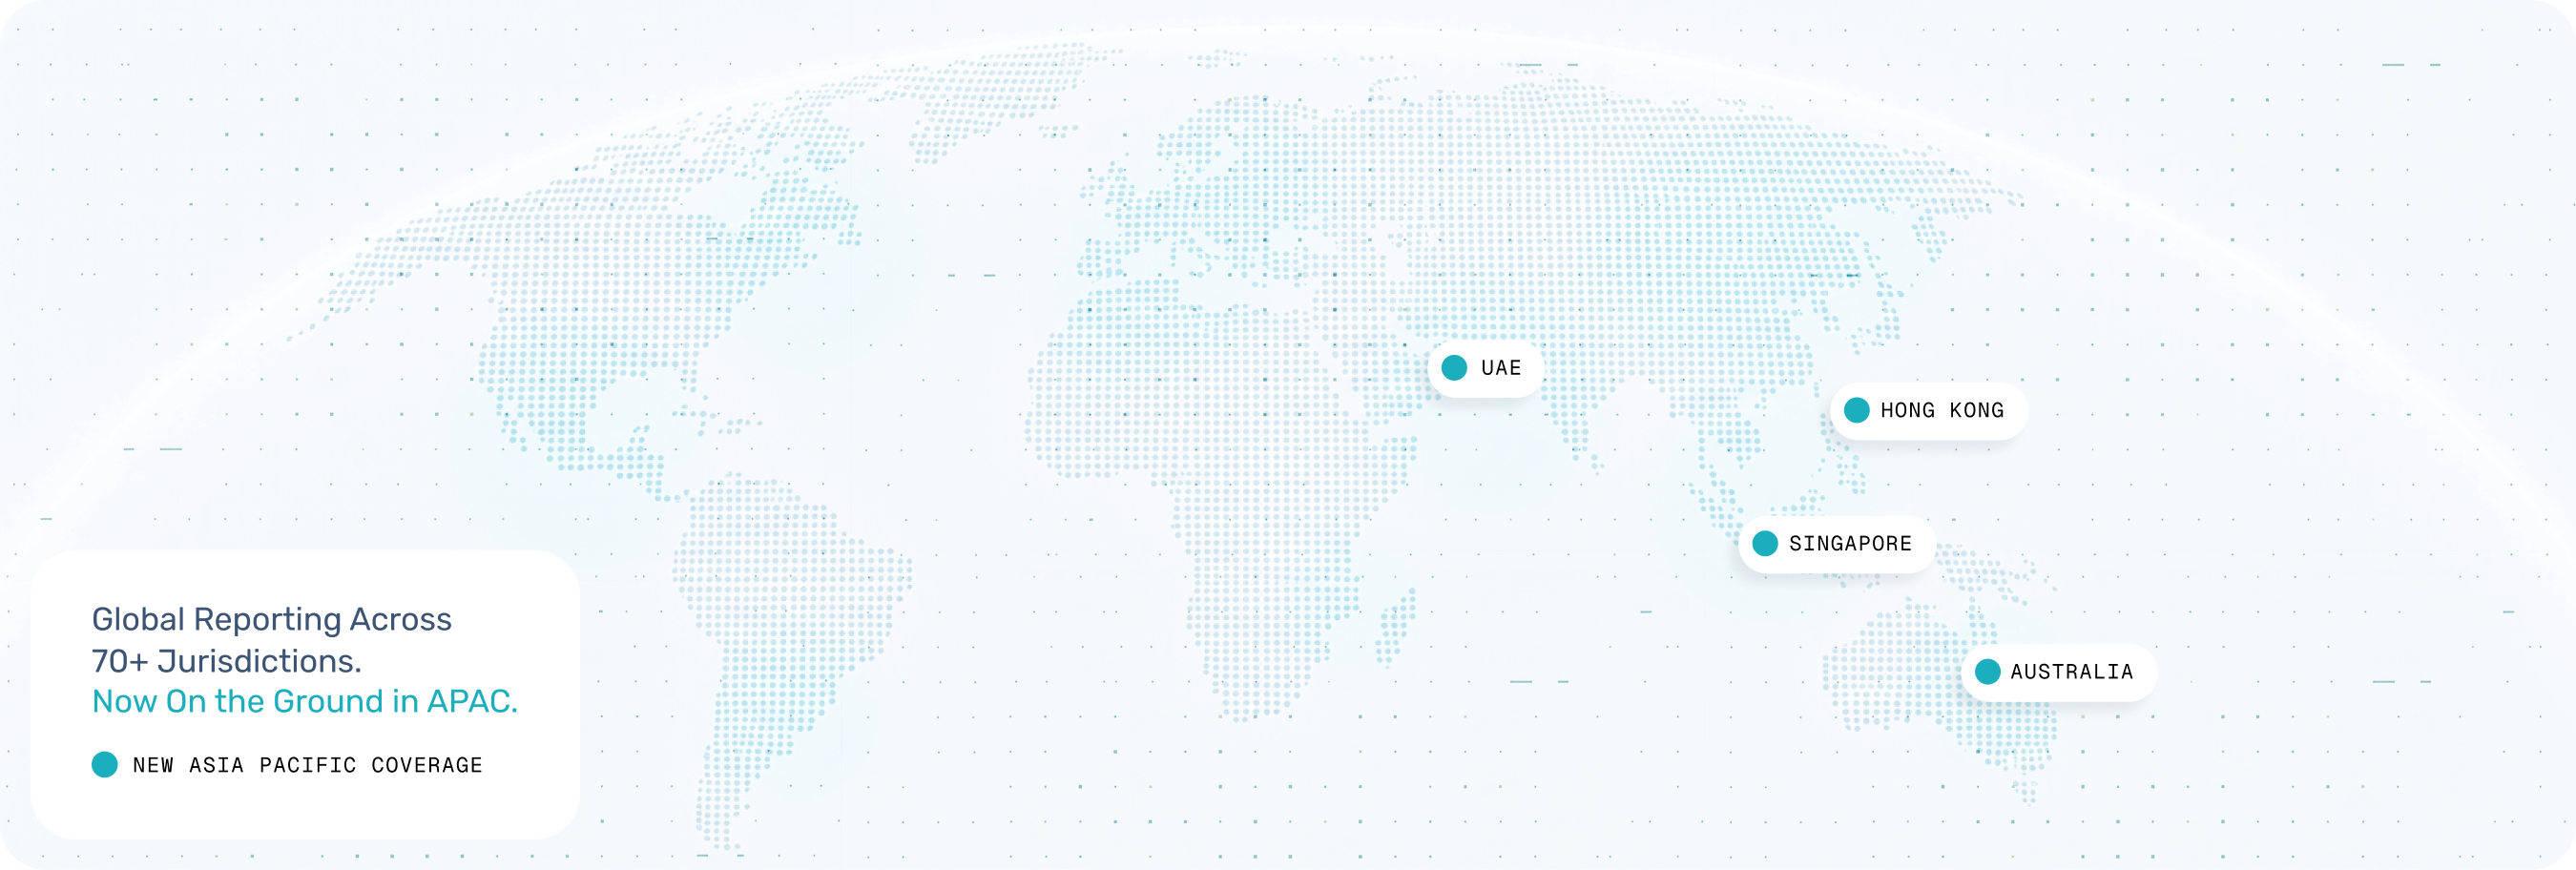
In APAC, Taxbit supports regulatory reporting across Singapore, Australia, New Zealand, the United Arab Emirates, and Hong Kong, with coverage expanding as jurisdictions publish new requirements. These sit within our broader global coverage of 70+ reporting jurisdictions.
Yes. The platform is modular. Teams can start with CARF and CRS 2.0 and extend into jurisdiction-specific reporting requirements on the same platform as their operating footprint grows.
No. Licensing and reporting scope are determined separately. Whether a platform is in scope for CARF or CRS depends on the activity it performs, not on holding a specific license, so obligations can apply with or without one.
Not sure which applies to your platform? Talk to one of our CARF specialists
CARF scope is based on activity, not company type. It applies to any business that effectuates crypto-asset transactions for customers, which can include exchanges, custodians, brokers, and payment or fintech platforms that handle digital assets. A platform with no crypto-asset activity is generally outside CARF, though it may have obligations under other reporting regimes.
Not sure which applies to your platform? Talk to one of our CARF specialists
CARF covers crypto-asset transactions at the transaction level. The amended CRS, often called CRS 2.0, covers financial account information and now extends to certain digital financial products, including some stablecoins and e-money tokens that fall outside CARF. Many platforms have obligations under both, and which applies depends on the products and services offered.
Read more: CARF and CRS 2.0: What's the difference?
Taxbit is API-first and connects to existing source systems through APIs and batch ingestion, with data collection embedded into current workflows rather than replacing them. Taxbit maintains the schema and jurisdiction-specific logic, so internal engineering does not have to re-implement rules as requirements change.