Book a Demo
Book a Demo

Compliance for the accounts you hold.

Digital banks, online brokers, and embedded banking products must report on both the payments they move and the balances they hold. Taxbit settles each customer's tax status at onboarding and files every return from the same account record.
Book a Demo

Solutions - Fintech


The stakes

An account is a reporting relationship.


Holding balances is a reporting obligation

Interest paid on customer balances carries 1099-INT. Offer crypto alongside it, and 1099-DA applies to the same account. That's two separate returns for one customer on one account.

E-money can put you in scope with no crypto at all

CRS 2.0 covers electronic money, with or without digital assets. A digital bank that's never touched crypto can find itself filing reports for the first time, new data to collect from customers and a new process to file it.

Status has to be settled at account opening

You need each customer's tax status before their first reportable transaction. Collecting W-9s and W-8s at onboarding keeps filing clean and avoids per-record penalties found at year end.

Tax work shaped like a project, forever

Every new product, market, or yield feature becomes another reporting build, scoped and staffed like a project. The rules keep changing regardless of engineering capacity, so the project never actually closes.

The difference

One account record for every return.


The old way

  • A separate reporting build for each product you launch
  • Engineering time spent on reporting logic instead of the product roadmap
  • W-8 and W-9 collection bolted on outside your onboarding flow
  • Discovering an e-money obligation after the reporting window opened
  • Interest, crypto, and payout reporting running as three processes

With Taxbit

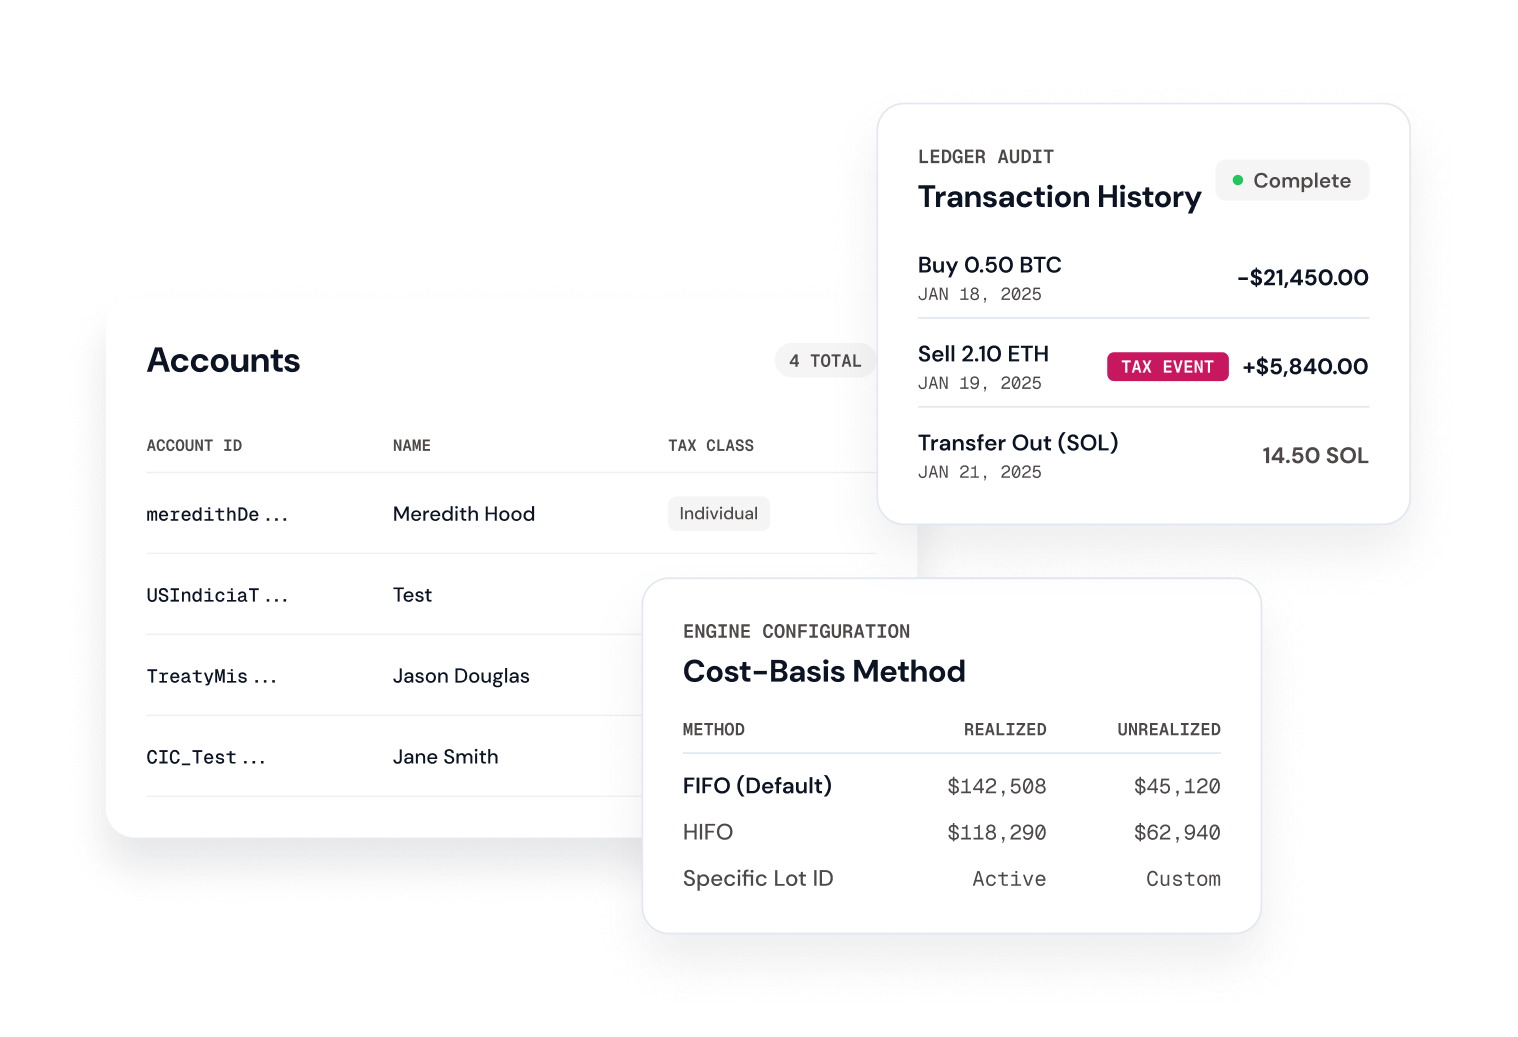
  • 1099-INT, 1099-DA, and 1042-S generated from the same account record
  • One rules engine across your products and markets, maintained as the rules change rather than rebuilt
  • W-8 and W-9 collected and validated at onboarding, inside your own product
  • CRS 2.0 scope worked out from the balances you already hold
  • New products using the reporting you already have, with nothing new to build

Built to load every transaction in real time.

"Before Taxbit, we couldn’t find a provider with an API that would allow us to load all of PayPal’s transactions in real-time. Uploading and reconciling huge files at the end of the year was not an option."

AI you can put in front of a regulator

Rules written into the system make the call on every account, and your team can read them. Every action the AI proposes is reviewed by a person before it runs.

A full audit trail

Every gain and loss traces back to the transactions behind it.

Your data stays yours

Taxbit does not train AI models on your data, and nothing is sent to third-party AI vendors.

SOC 2 and enterprise controls

The security documentation your team asks for before a deal closes, ready for review.

Fintech reporting, answered.

We hold customer balances but have no digital assets. Are we in scope for CRS 2.0?

Possibly, yes. CRS 2.0 covers electronic money whether or not digital assets are involved, so e-money institutions, payment platforms, digital banks, and wallet providers that hold balances for customers can be in scope with no digital assets anywhere in the product. For many of them it is the first obligation of this kind, which means collecting data from customers they have never had to ask for, and standing up a process to file it.

We run a digital bank or embedded banking product. Which forms apply?

Interest paid on customer balances carries 1099-INT. If you offer digital assets alongside it, 1099-DA applies when a customer sells or exchanges them. US-source income paid to non-US persons carries 1042-S with withholding, and payouts over card and third-party networks carry 1099-K. Taxbit generates all of them from the same account and transaction data, with W-9 and W-8 collected at onboarding and TINs checked against the issuing authority in real time.

What does a digital bank have to collect from customers for information reporting?

Enough to know each customer's tax status before their first reportable transaction: a W-9 for US persons, a W-8 for foreign persons and entities, and a CRS 2.0 self-certification where that regime applies. Taxbit collects all of it through an SDK that runs inside your own product, so the customer never leaves your app. US TINs are matched against the IRS in real time, foreign tax IDs and VAT numbers are validated by format, and each customer's status is watched after onboarding in case it changes.

How do information reporting and withholding work across domestic and foreign customers?

Your US customers and your foreign customers need different paperwork, different checks, and different forms at the end of the year, even when they hold the same kind of account with you. Taxbit collects and checks both W-9 and W-8 in the same onboarding flow, keeps each customer's withholding status on the account record, and generates 1099 and 1042-S from that same record, so the whole account base is handled in one system.

See it against your own data.

Balances and payments reported from one account record, without rebuilding for each new product.
Book a Demo