
Banks, brokerages, and custodians are entering digital assets while CRS 2.0 pulls crypto into a regime they already report under. Taxbit folds the new activity into the reporting you already trust, reconciled and ready to defend.
The stakes
New activity, existing reporting
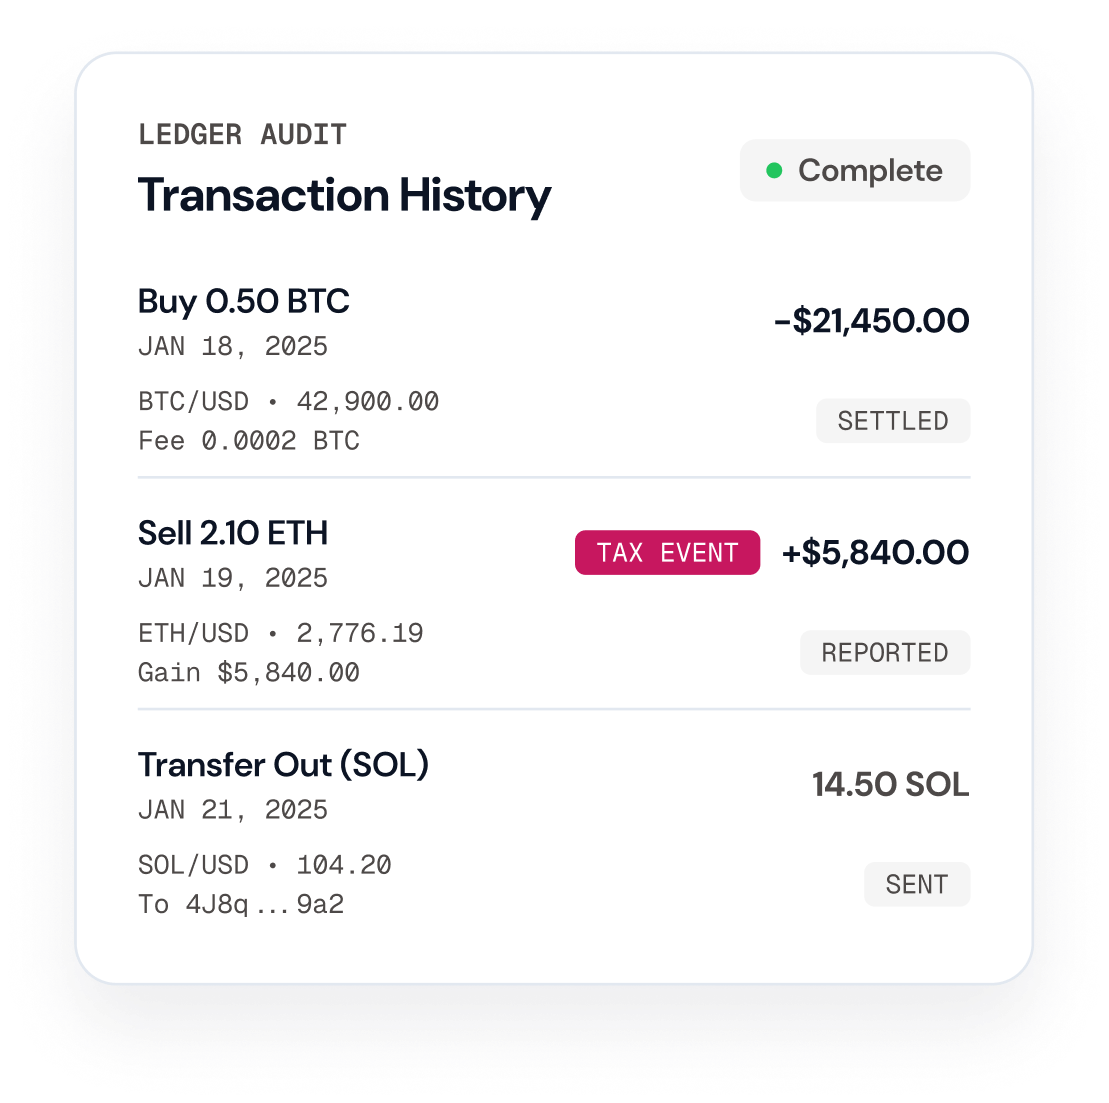
Digital-asset activity has to land inside the reporting you already run, in the same record your institution has to defend.
CRS 2.0 now pulls in crypto
CRS 2.0 brings digital assets into a regime you've reported under for years. The filings are the ones you already know. What's new is the asset class behind them and the data it produces.
Two regimes, reconciled
Old and new reporting have to agree. Matching the rules you have followed for years against the digital-asset rules, on the same accounts, is where institutions get exposed.
Defensible, or it doesn't count
Your standard for traditional assets doesn't relax for crypto. The day an examiner asks why, you have to re-run every call and point to the rule behind it.
Who you are
Tax leads
The same accuracy and audit standard you hold for every other asset class, extended to digital assets. Every call can be re-run, and the rule behind it is cited.
CFOs
Enter a new asset class without building a new operation to run it. One platform instead of a build, a vendor, and a maintenance budget.
Compliance officers
Digital-asset activity inside the audit trail you already trust. When the examiner asks why, the answer is in the system.
Heads of digital assets
Launch the product without the reporting becoming the bottleneck. Crypto folds into the reporting the firm already runs.
The difference
The old way
With Taxbit
AI you can put in front of a regulator
Rules written into the system make the call on every account, and your team can read them. Every action the AI proposes is reviewed by a person before it runs.
A full audit trail
Every gain and loss traces back to the transactions behind it.
Your data stays yours
Taxbit does not train AI models on your data, and nothing is sent to third-party AI vendors.
SOC 2 and enterprise controls
The security documentation your team asks for before a deal closes, ready for review.
CRS 2.0 extends the standard you already report under to electronic money, central bank digital currencies, regulated stablecoins, and indirect digital-asset exposure such as derivatives and funds. For an institution already reporting under CRS, this is an extension of work you already do rather than a new build: more products in scope, tighter rules, and the same exchange mechanism. What counts as a regulated stablecoin is decided country by country, so scope varies by market.
A self-certification establishes the account holder's status for reporting: residence address, every jurisdiction of tax residence, a taxpayer identification number for each of those jurisdictions, and date of birth for individuals. Entity accounts also need the CRS classification and, where that classification requires it, controlling persons with their own residence and taxpayer identification numbers. Taxbit collects and validates it in the same flow as W-9, W-8, and CARF self-certification.
The hard part is that domestic and foreign payees need different paperwork, different checks, and different forms, even though the payments behind them sit in one ledger. Taxbit collects W-9 for US persons and W-8 for foreign persons and entities in one flow, checks the identifiers each one carries, and generates the resulting returns from the same source data. Withholding status stays on the account record instead of being tracked somewhere else.
Yes, where the fund has reports to file. CRS 2.0 reaches indirect digital-asset exposure, including funds that earn investment income from digital assets, and the work is the same work Taxbit already runs for banks and brokers: establish who the account holder is, determine who is reportable and in which jurisdiction, and generate the filing in that authority's format.
From real-time payment data to the right return for each payee, built for high transaction volume.