
February 05, 2026 | On Demand
CARF and the revised CRS rules are no longer theoretical — they’re becoming enforceable global standards that will directly impact crypto platforms, customer onboarding, and transaction reporting.
This on-demand masterclass brings together regulatory and industry experts for a practical deep dive into the Crypto-Asset Reporting Framework (CARF): what it is, how it’s rolling out globally, and what crypto-asset service providers must do now to prepare.
Hosted by Max Bernt (Managing Director, Europe at Taxbit), the session features Dion Seymour (Director at Andersen) and Colby Mangels (Taxbit), who previously worked at the Organisation for Economic Co-operation and Development on the development and implementation of CARF itself.
Together, they unpack how CARF moved from concept to regulation — and what operational readiness really looks like as jurisdictions move toward enforcement.
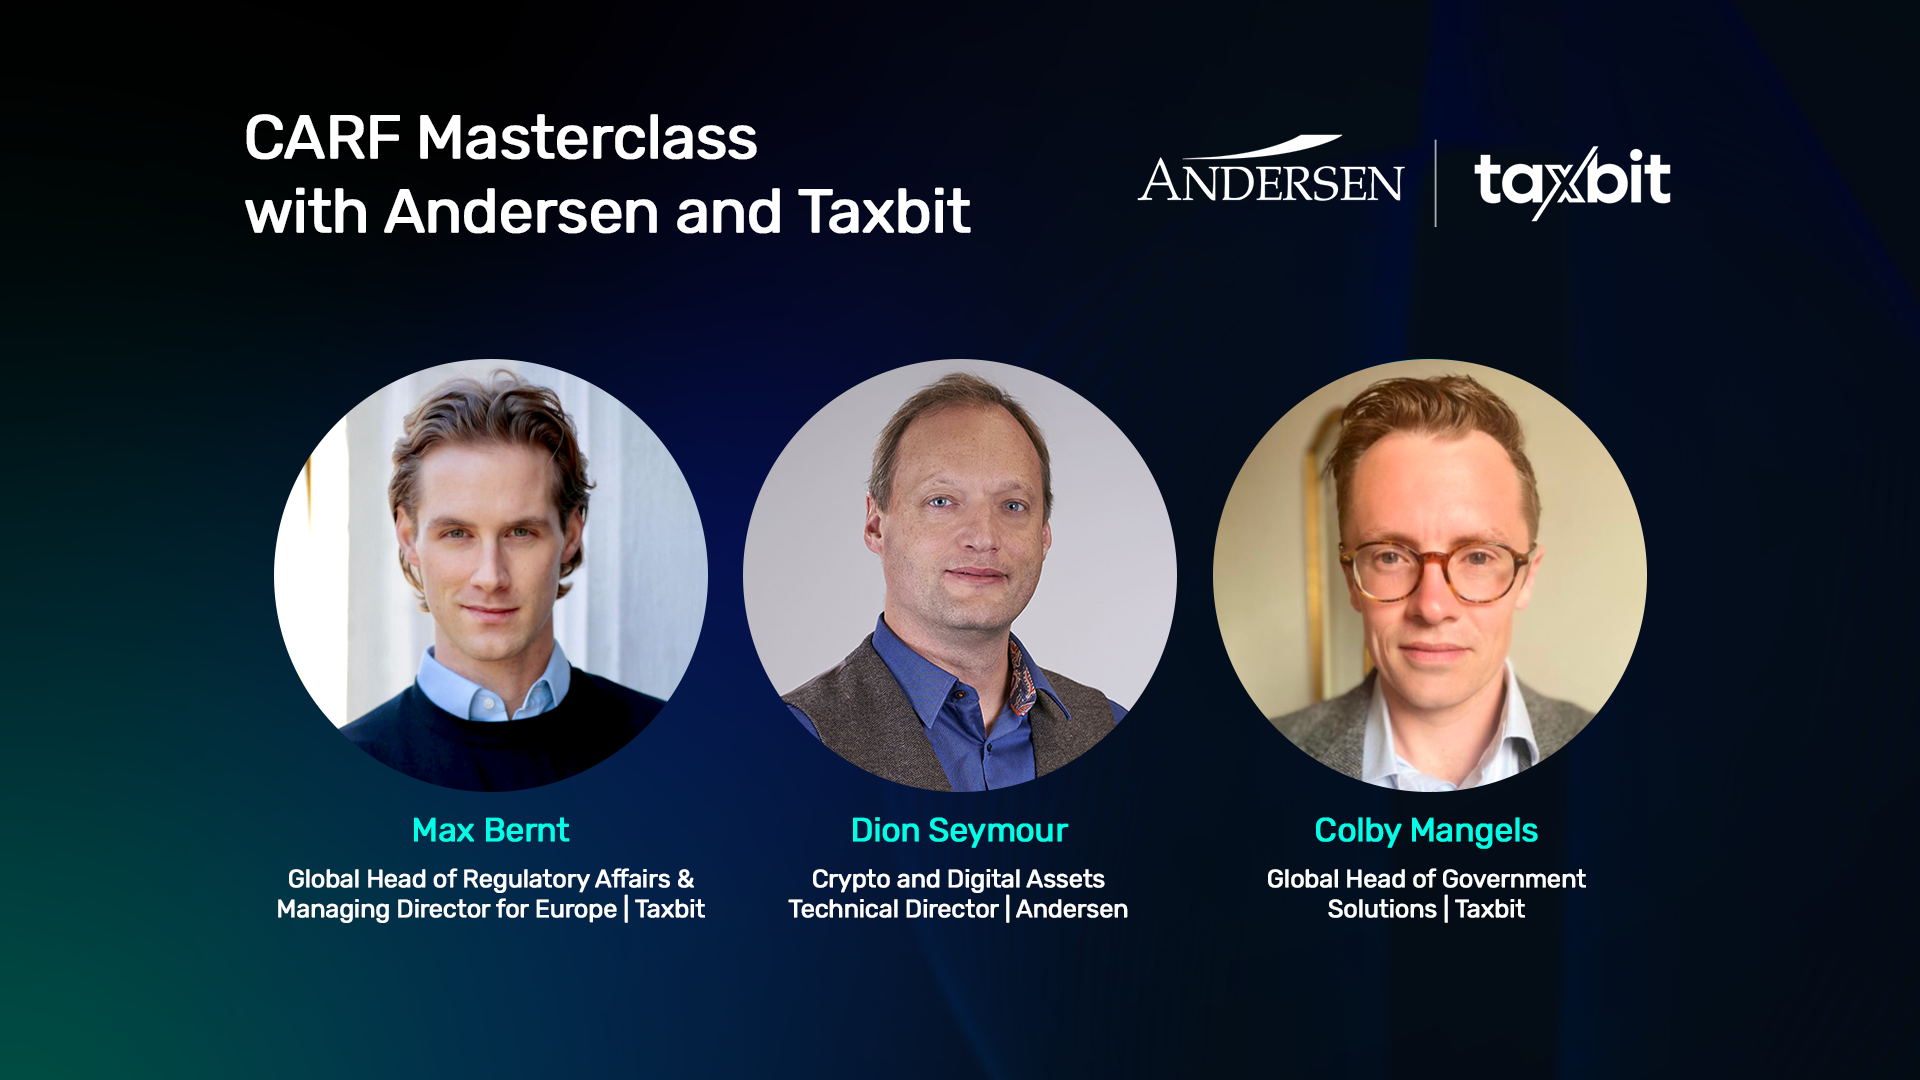
Speakers:
Max Bernt – Taxbit
Dion Seymour – Andersen
Colby Mangels – Taxbit
Book a demo to see your own accounts and products filed end to end.